

Disclosure: We own this one.
Today we have an update on Outdoor Holding Company, a company that we provided a full update on September of last year – “Ammo Inc. no longer - Outdoor Holding Company NASDAQ: POWW hits the reset button at the AGM”. https://www.canadianvalueinvestors.com/p/ammo-inc-no-longer-outdoor-holding Full archives: https://www.canadianvalueinvestors.com/t/poww
The turnaround of America’s eBay of guns is going better than we expected. The ammunition business is gone, legacy costs have declined substantially, and GunBroker is showing improving revenue and profitability.
The market, in our view, still has not fully recognized the earnings power of the surviving business. We recently increased our position.It is cash rich, high ROE business repurchasing shares and trading for ~11x our estimate of cash-adjusted FCF. We recently purchased more averaging ~$2.30.
How Screens Fail You
What We Said A Year Ago
Business Performing
Note on Intangibles
And Then Repurchases
Bottom Line: POWW Today
Appendixes
Disclaimer - The content contained in this blog represents the opinions of contributors. You should assume contributors have positions in the securities discussed, whether long, short, or somewhere in between, and that this creates an obvious bias and conflict of interest regarding the objectivity of this blog. Statements in the blog are not guarantees of future performance whatsoever and are subject to certain risks, uncertain risks, and other factors. Information might also be completely out of date and may or may not be updated. In addition, no one guarantees the accuracy of any information provided and none of the information should be construed as investment advice or any other kind of advice under any circumstance, and the blog is a blog and not a registered investment advisor or broker in any jurisdiction. Frankly, no information here should be used for any purpose, except for entertainment (and we hope you enjoy).
How Screens Fail You
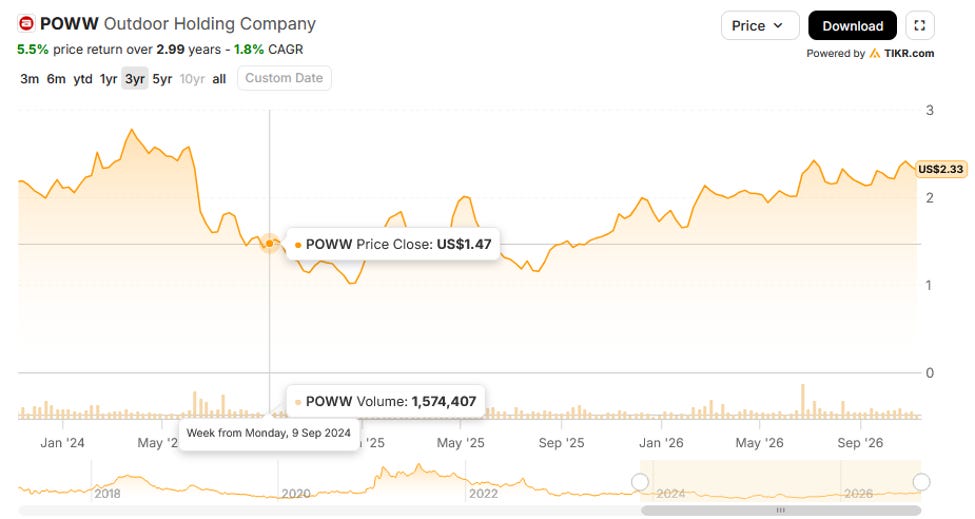
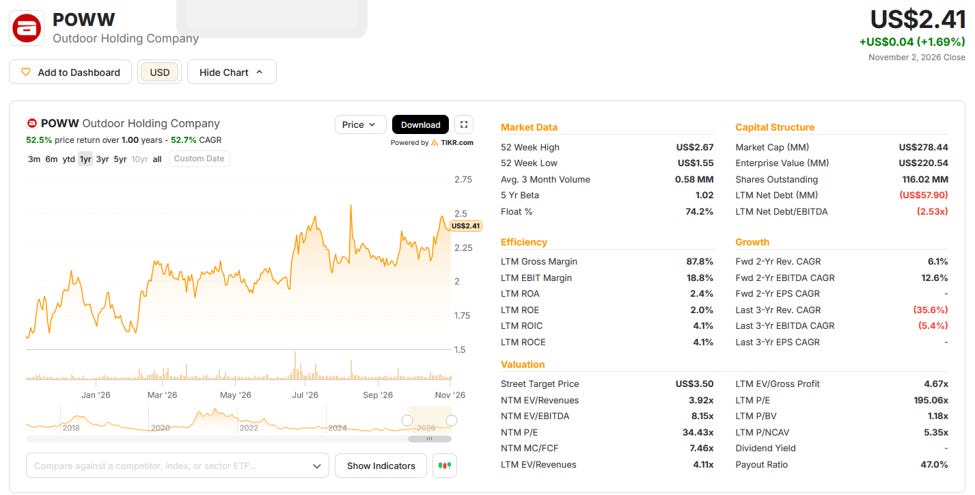
Here are snapshots from Fiscal.AI and TIKR. They are, in general, technically correct. But, they miss the story. Gunbroker was a business that was held within AMMO, which was burdened by a now-gone-loss-making ammunition manufacturing business that never got off the ground. Now that Gunbroker stands on its own with legacy AMMO management and legal problems gone, we are starting to see the strength of the business (and screens won’t show it until sometime next year).
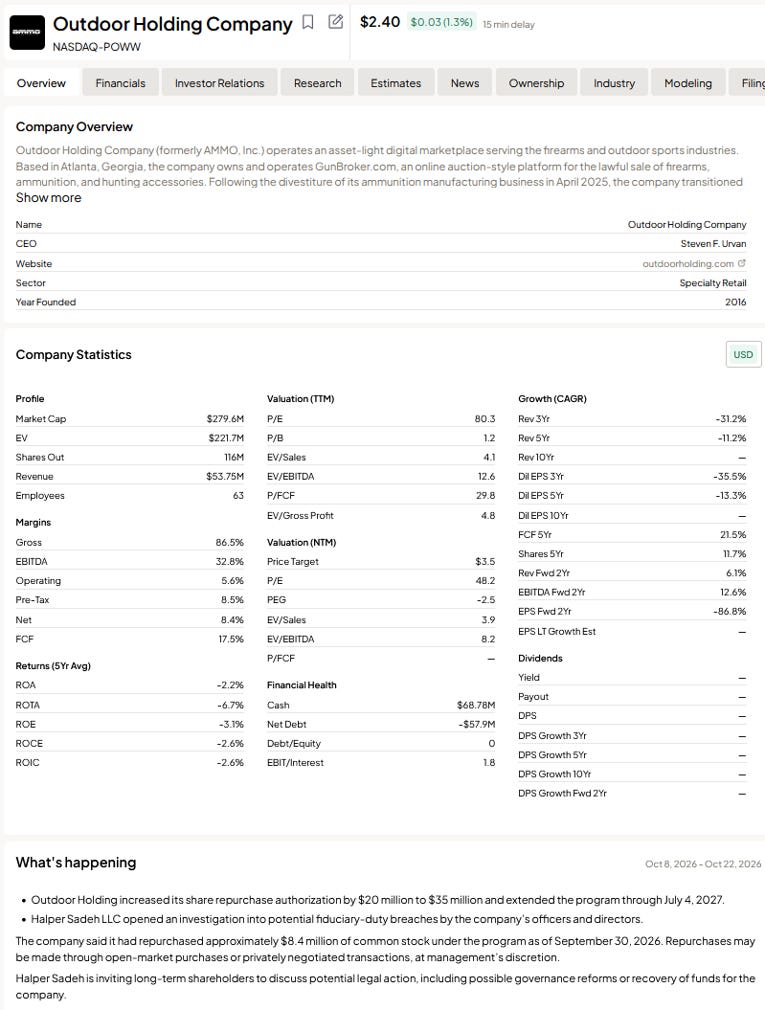
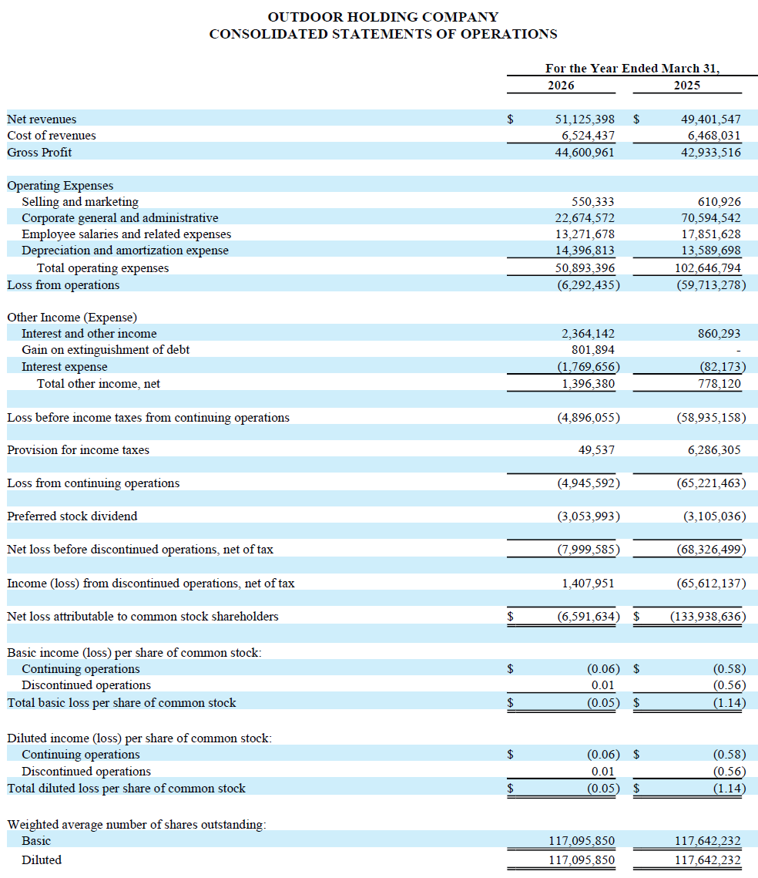
The raw statements are indeed noisy.
What We Said A Year Ago
We said:
Ultimately, they are trading at an undemanding normalized multiple for a high margin, low capital business. Now they just need to get out of their own way and run it. We wish Steve luck.
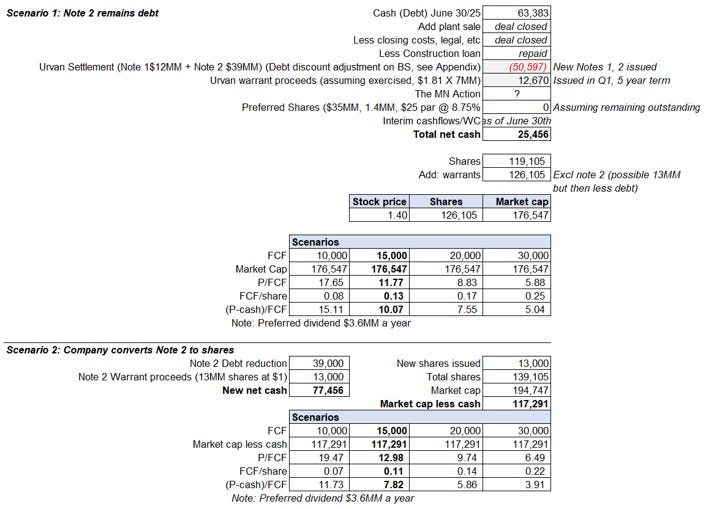
Since then, they seem to have done the right things and the Gunbroker founder-now-boss has been reasonable. Not to rehash the story (you must read the backgrounder), but it appears that the founder wants to move on and run the business. POWW followed scenario 2. The Company exercised a contractual option to extinguish the $39MM note by issuing Urvan additional 13 million warrants at $1/each, which we view as quite a reasonable trade for the Company given the share price was ~$1.40. He took a salary of $1 for his first year. See Appendix: Note 2 Converted, $1 Salary
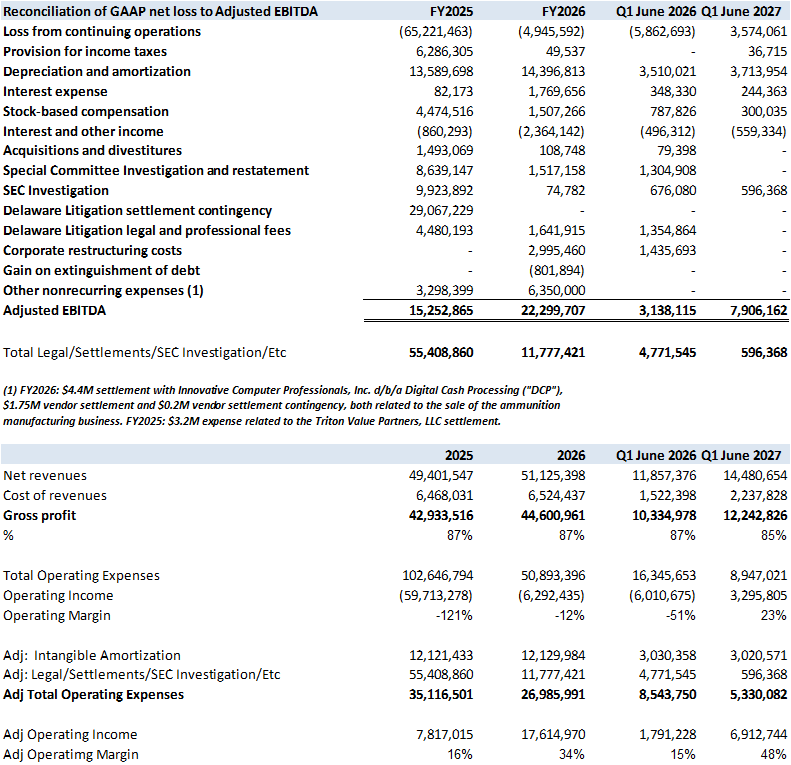
When looking through the noise (being legal settlements and costs of over $65MM!), you have an underlying business that is generating good margins even while being burdened by high G&A and operating costs (that are now being reduced).
Business Performing
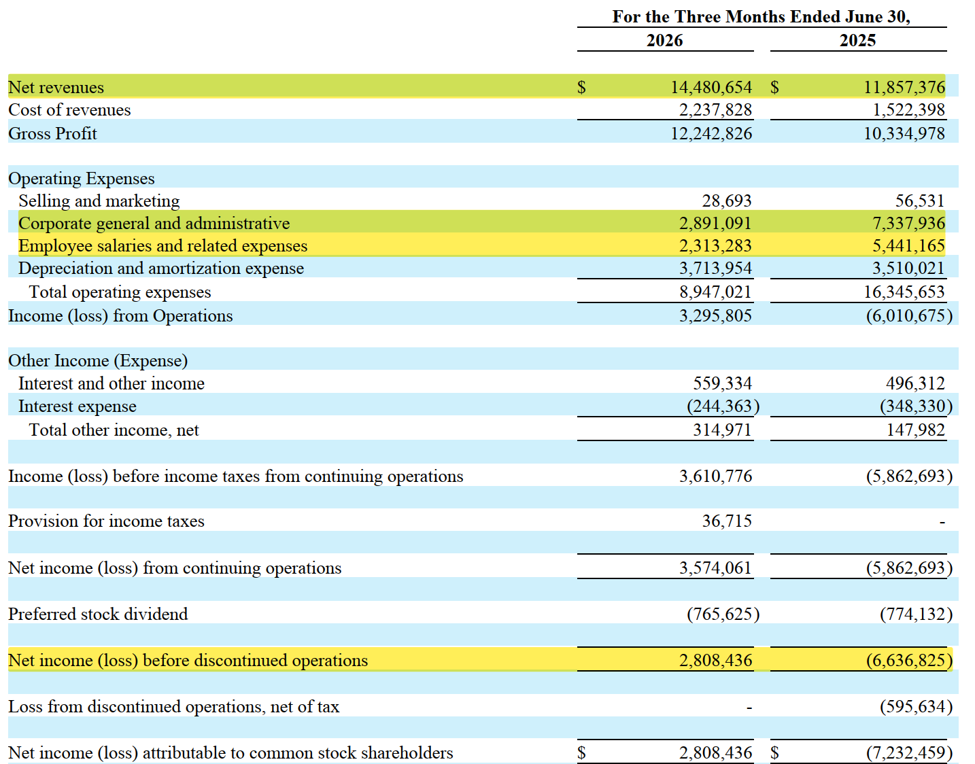
What has surprised us is the performance in the Gunbroker outside of just legal distractions and one-time costs rolling off. We did not fully appreciate the potential for underlying business itself to improve by management that is no longer distracted. There has been increased sales (>20%), better profitability, higher FCF. GMV has grown and they have monetization from the new Master Federal Firearms License (FFL) transfer service. There was some benefit from Virginia (increased restrictions on transfers of certain guns after July 1st, subject to ongoing legal battles), but growth occurred outside of this. The financials still do not tell the full story.
At the Q4 call:
Quarterly adjusted EBITDA grew from $3.1 million to $4.9 million to $6.6 million to $7.7 million from the first to fourth quarters, respectively. For the full year, adjusted EBITDA improved to $22.3 million from $15.3 million in fiscal 2025. We are outperforming the run rate of $25 million adjusted EBITDA that I set as a goal just 10 months ago. I’m especially proud of the tremendous work our team undertook during fiscal 2026 to overhaul and strengthen our financial reporting infrastructure, culminating in the successful remediation of all previously identified material weaknesses in our internal control over financial reporting by year-end.
Note on Intangibles
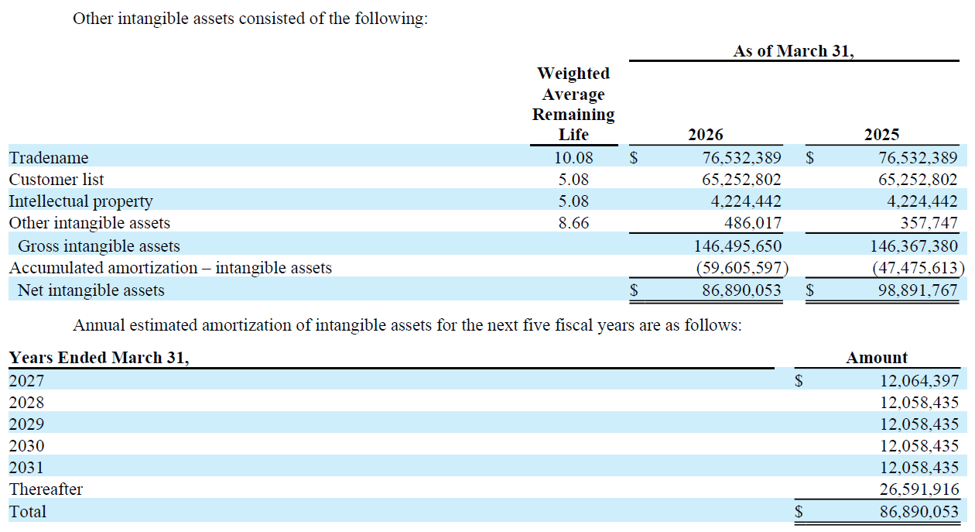
Because of the bizarre outcome of Gunbroker effectively completing a coup and selling off the ammunition business, the Company is depreciating its own customer relationships it purchased from itself. This is the technically correct accounting, but obviously should be adjusted to calculate owner earnings. This is the definition of a non-cash expense.
This is material. Accounting earnings will be suppressed until 2033 while the underlying business will actually be earning $12 million more per year than the headline net income number.
NOTE 12 – INTANGIBLE ASSETS
On April 30, 2021, we entered into an agreement and plan of merger (the “Merger Agreement”), by and among the Company, SpeedLight Group I, LLC, a Delaware limited liability company and a wholly owned subsidiary of the Company and Gemini Direct Investments, LLC, a Nevada limited liability company (”Gemini”), whereby SpeedLight Group I, LLC merged with and into Gemini, with SpeedLight Group I, LLC surviving the merger as a wholly owned subsidiary of the Company (the “Merger”). At the time of the Merger, Gemini had nine subsidiaries, all of which are related to Gemini’s ownership of GunBroker, an online auction marketplace dedicated to firearms, hunting, shooting, and related products. The intangible assets acquired include a tradename, customer relationships, intellectual property, software, and domain names. Total amortization expense of our intangible assets was $12,129,984 and $12,121,433 for the years ended March 31, 2026 and 2025, respectively.
And Then Repurchases
The Company has started significant share repurchases.
