

Disclosure: We are long GRVY.
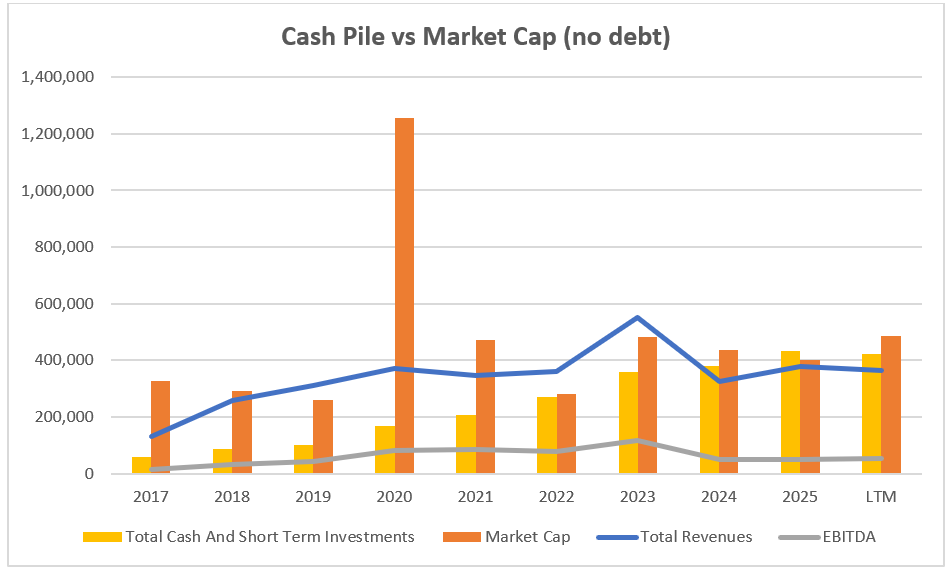
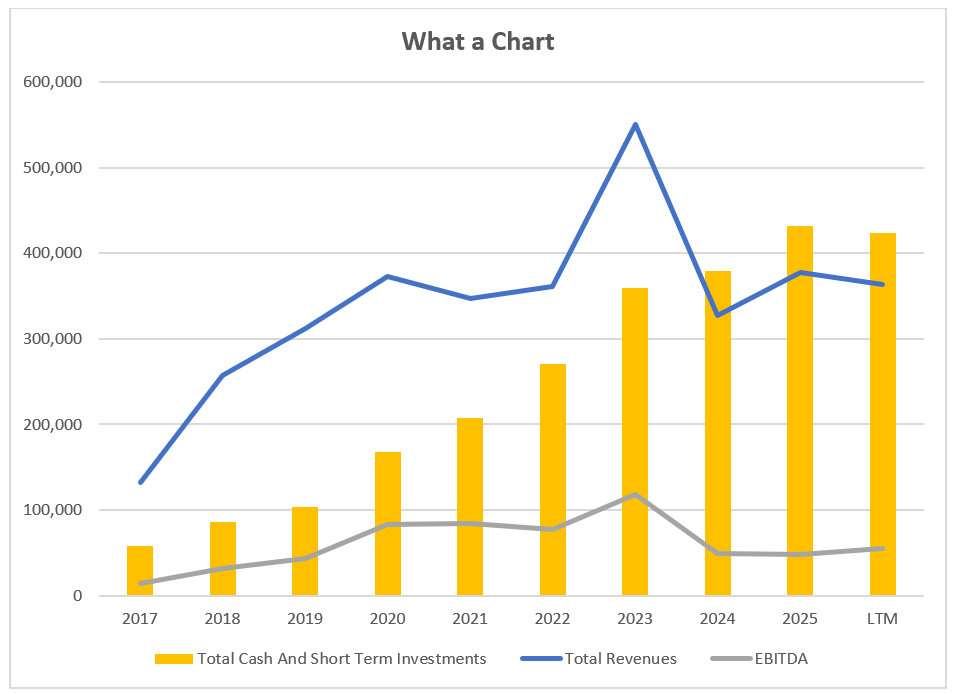
Today’s story is about Ragnarok, a gaming franchise owned by Gravity Co. GRVY that has been going since 2002. Why has this piqued our interest? The chart below explains it. How does a company end up with half a billion dollars in cash, just shy of their market cap, no debt, and a single digit PE (approximately 1x cash-adjusted)? Well, in this case it is due to poor corporate governance combined with it being a Korean-but-ADR-listed company majority-owned by a Japanese company. However, a recently announced dividend, their first ever, and major changes at the public parent level leads us to believe that this might not be a total value trap for much longer.
The Franchise
Activision-Blizzard at the Time
The Value Trap
Hey Ho, GungHo, Management Has Got to Go
Sony Alliance
Changing Capital Allocation
What is the Excess Cash Anyway?
Disclaimer - The content contained in this blog represents the opinions of contributors. You should assume contributors have positions in the securities discussed, whether long, short, or somewhere in between, and that this creates an obvious bias and conflict of interest regarding the objectivity of this blog. Statements in the blog are not guarantees of future performance whatsoever and are subject to certain risks, uncertain risks, and other factors. Information might also be completely out of date and may or may not be updated. In addition, no one guarantees the accuracy of any information provided and none of the information should be construed as investment advice or any other kind of advice under any circumstance, and the blog is a blog and not a registered investment advisor or broker in any jurisdiction. Frankly, no information here should be used for any purpose, except for entertainment (and we hope you enjoy).
The Franchise
We have followed Gravity Co for a few years now, a story that goes back to 2023 when we were investing in the Activision-Blizzard merger (a fun and lucrative adventure covered later below). Ragnarok began as Ragnarok Online, a Korean PC MMORPG developed by Gravity using the fantasy world of Lee Myung-jin’s Ragnarok comic. Closed and open beta testing began in 2001, followed by commercial launches in Korea, Japan and Taiwan in 2002 and then on to China, Thailand, Indonesia, the Philippines, the U.S. and other international markets. The distinctive style and persistent online world made it one of Korea’s early globally successful MMORPGs with over 67 million users and 1 trillion KRW (US$700MM+) over time. This is an Asian phenomenon with minimal sales in North America (our informal survey of friends led to some nostalgic discussions about their childhoods in Asia).
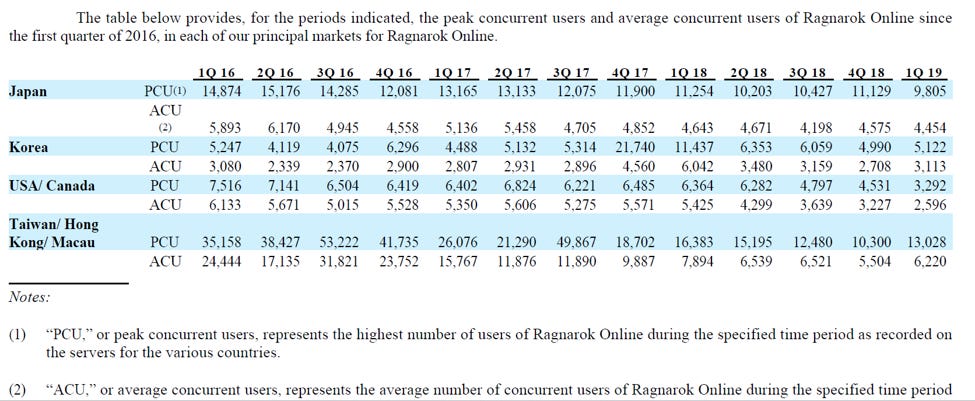
Ragnarok online is long-lived. My goodness. It has been continually updated and the game is still played. Here was performance back in 2016.
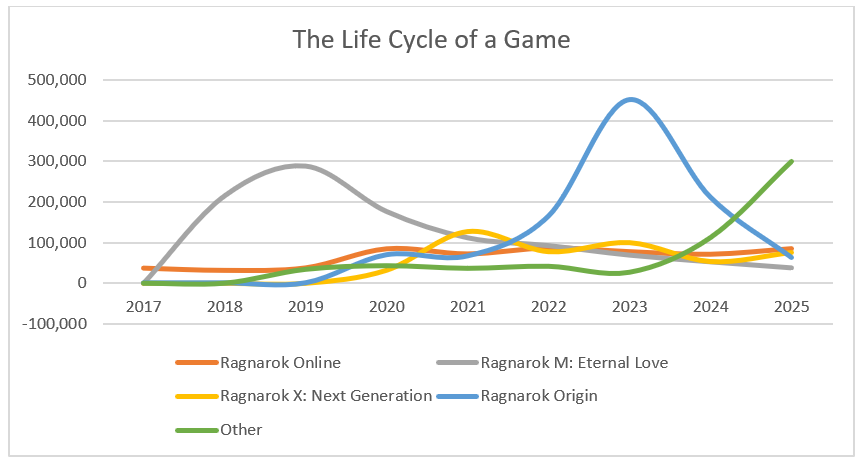
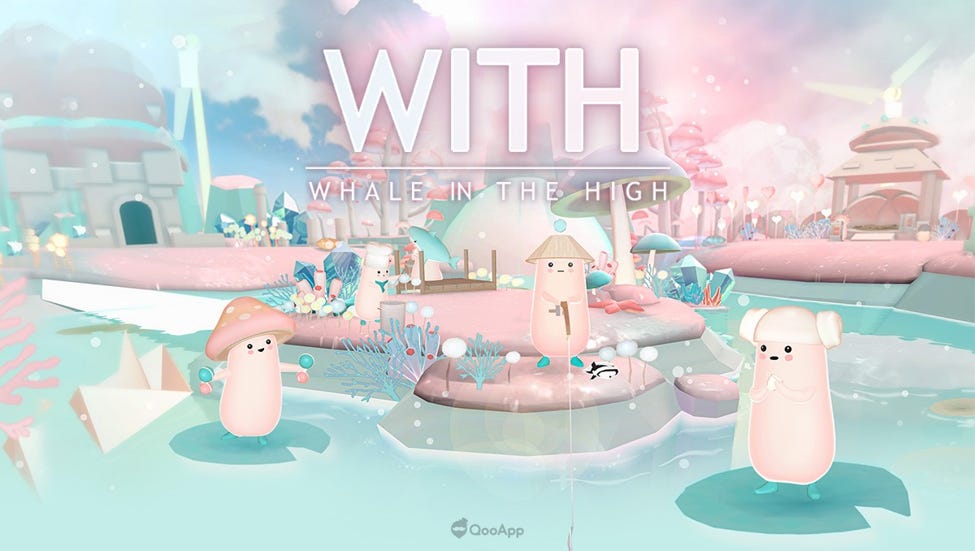
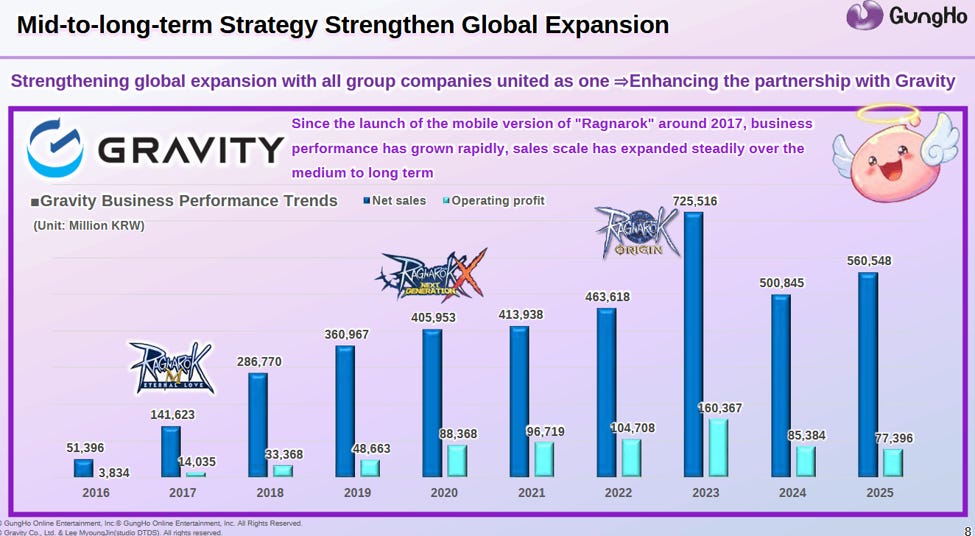
But they are also working on sequels that have been successful (see chart below). They have been successful at creating new Ragnarok titles and expanding the IP. Is this revenue diversification? We acknowledge it is still driven by their one key franchise. But, they are also working on new games and franchises. Our favourite over the years was the somewhat bizarre Whale in the High (WITH), “a relaxing, cozy mobile idle game where players build a serene village and interact with miniature creatures on the back of a giant flying whale”. We downloaded the game and can confirm it is extremely cute.
To be clear, their products are an Asia phenomenon, originally Korea/Japan/Taiwan, but now also other countries like Thailand and Indonesia are material.
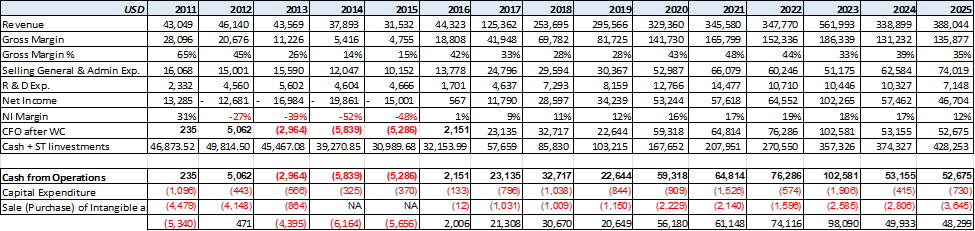
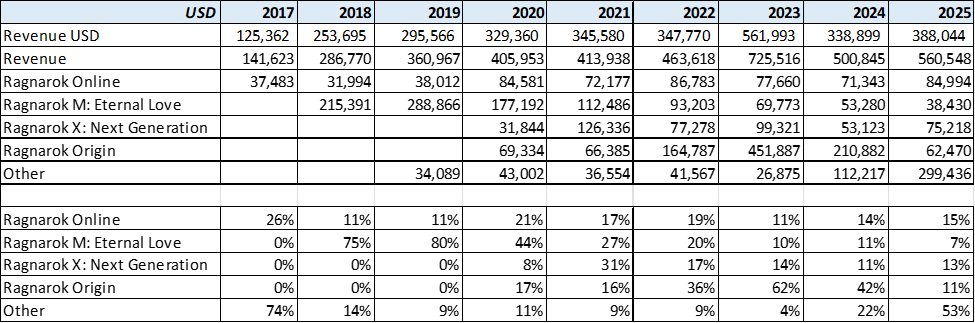
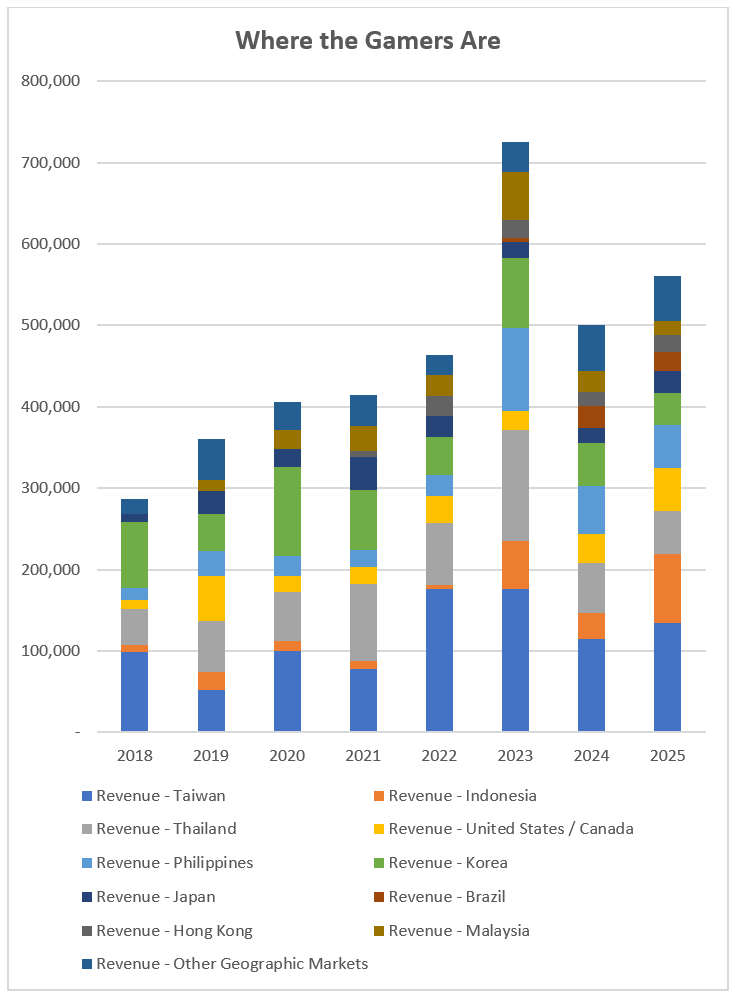
Over the next two decades, Gravity shifted Ragnarok from a single PC MMORPG into a franchise built around repeated reinterpretations of the same IP. Attempts included Ragnarok Online 2, browser and casual games, but the major transformation came with mobile: Ragnarok M: Eternal Love, followed by frequent releases (Ragnarok Origin, Ragnarok X: Next Generation, Ragnarok M: Classic, etc). Gravity increasingly localized launches country by country and built publishing subsidiaries across Asia, while monetization moved toward free-to-play mobile mechanics, automated progression and in-game purchases.
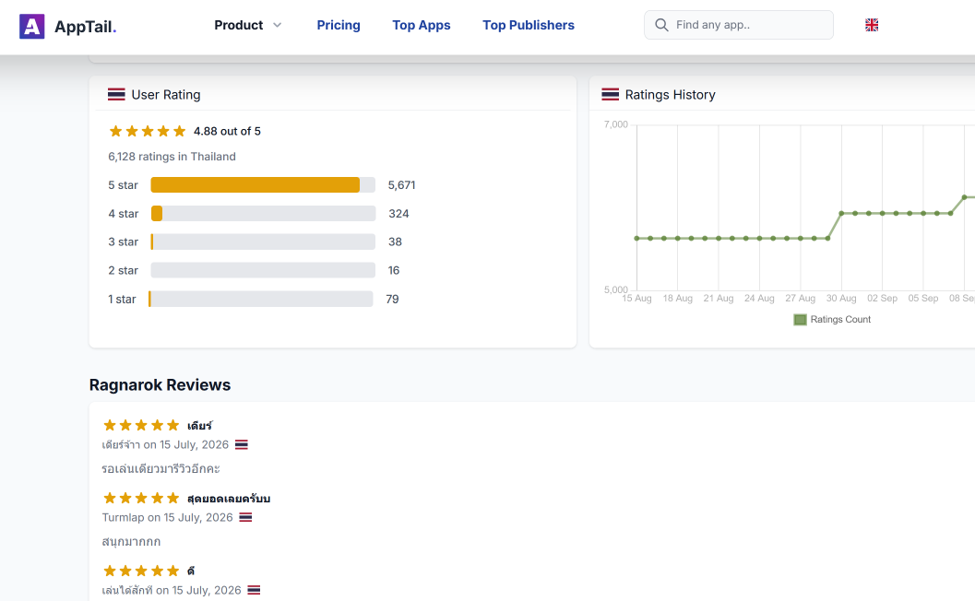
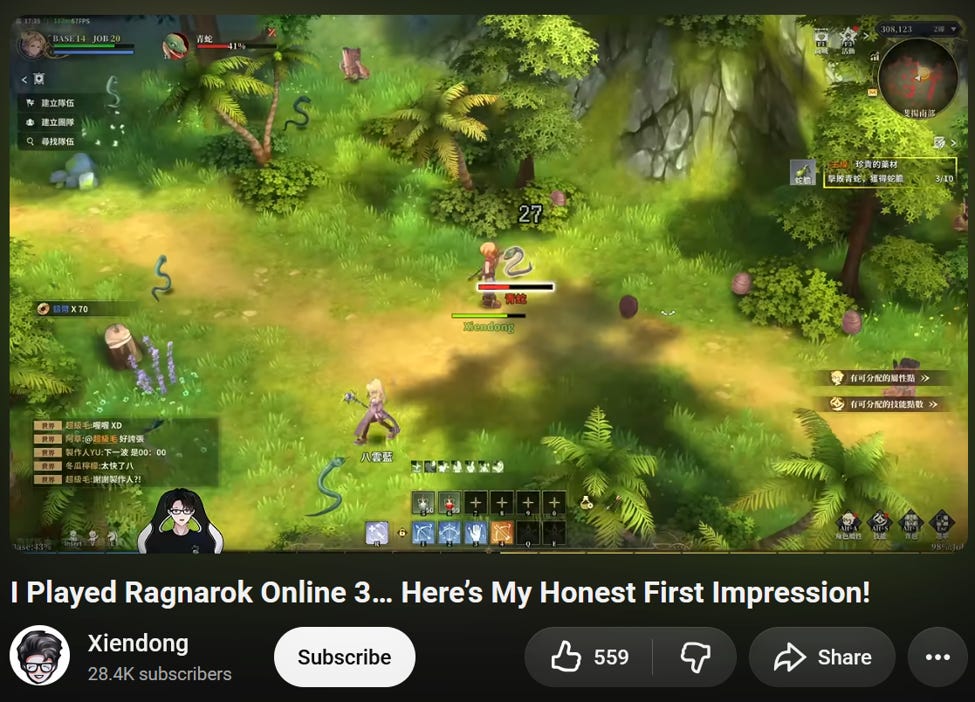
Releases often have a short shelf life and require constant replacement and are typically smaller releases. However, the latest releases are more ambitious. Ragnarok: The New World, the franchise’s first open-world MMORPG, launched in Taiwan/Hong Kong/Macau in January 2026 and reached #1 in the Apple App store in those markets and helped drive Q1 mobile revenue up over 50%. Revenue from the game then declined in those initial markets in Q2, although its July Southeast Asian rollout has shown fresh traction in other markets like Thailand. Ragnarok Online 3 is the next major release. The overall strategy now appears to be moving beyond simply producing more mobile sequels toward making Ragnarok a broader, multi-platform entertainment franchise while still relying on a steady stream of new game launches to offset the decay of older titles. Ragnarok: The New World is currently doing well in Thailand for example. We also highlight some Ragnarok Online 3 gameplay below.
Activision-Blizzard at the Time
The full story is we first were looking at this back in 2023 when the Activision-Blizzard merger fight with the FTC was happening.
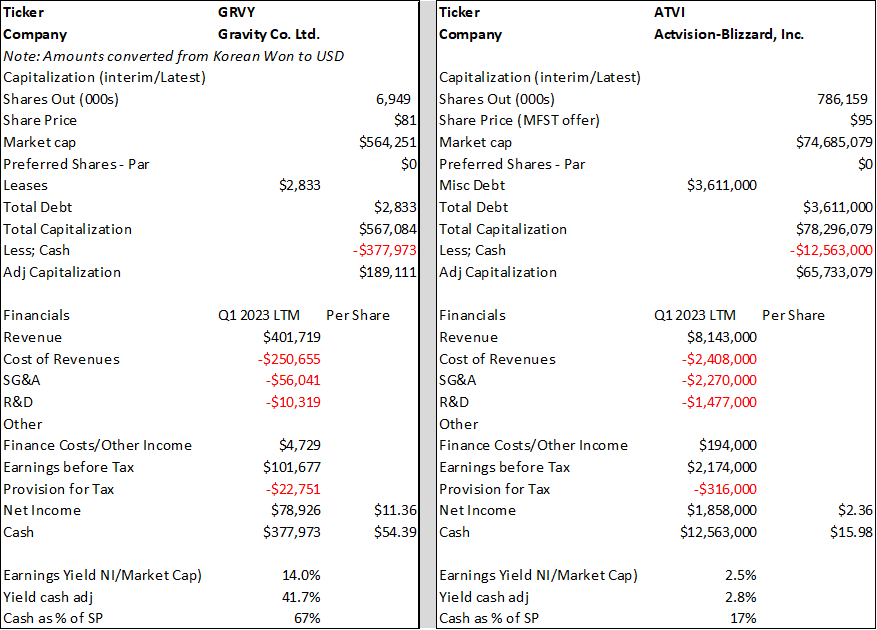
Gravity Co. NYSE:GRVY and Activision-Blizzard NYSE:ATVI – Thinking about relative value

Provided to subscribers July 19, 2023. Disclosure: We own both GRVY and ATVI at time of posting.
-The FTC tried to block the merger and lost - https://www.bloomberg.com/news/articles/2023-07-12/ftc-to-appeal-judge-s-go-ahead-for-microsoft-activision-deal
-The FTC tried to appeal, and was blocked https://www.bloomberg.com/news/articles/2023-07-14/ftc-loses-appeals-court-bid-to-pause-microsoft-activision-deal “Court ruling is a blow to the US agency and Chair Lina Khan” – We agree. It is probably better that the FTC focuses on more important things than many gaming consoles kids can play Call of Duty on.
At the time ATVI was trading at ~$92 vs the offer of $95 plus $0.99 dividend. With an expected timeline of three months or less the IRR was ~17%. We ended up buying (along side Warren Buffett it later turned out, a humble brag we will hold onto). We also started selling call options above the offer price; if a very unlikely competitive offer did come through, we would still have had some of the upside. No other offer ever came, the deal closed, and premiums were kept.
We did not end up being a shareholder of GRVY. Our concerns were: 1) there was no catalyst, and 2) the risk that GungHo would do something like a take-under of minority shareholders. We still fret about #2.
The Value Trap
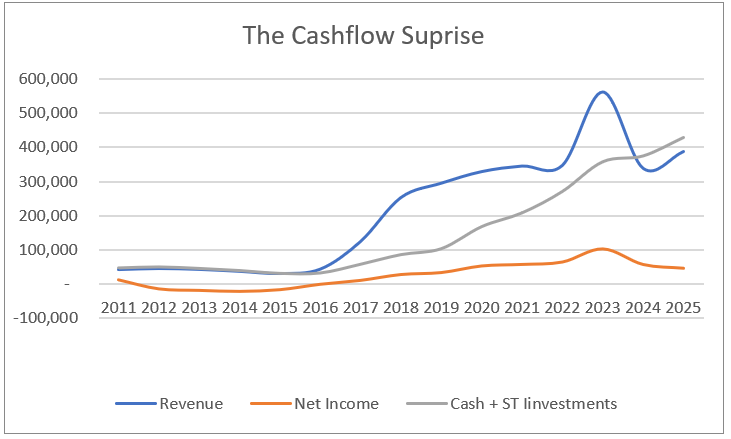
At the time Activision-Blizzard was a much better business, full control (vs GRVY no control), and in general deserved a higher multiple. But, let us not forget that Activision-Blizzard is really just a few franchises, albeit extremely successful ones.
Today, adjusting for cash on hand, Gravity is trading at 1-2x earnings. Should Gravity trade at similar multiples to Microsoft’s sweetheart offer price for ATVI? Absolutely not, but maybe GRVY continues to trade too cheaply relatively and absolutely. We thought so, but just needed a catalyst.
Hey Ho, GungHo, Management Has Got to Go
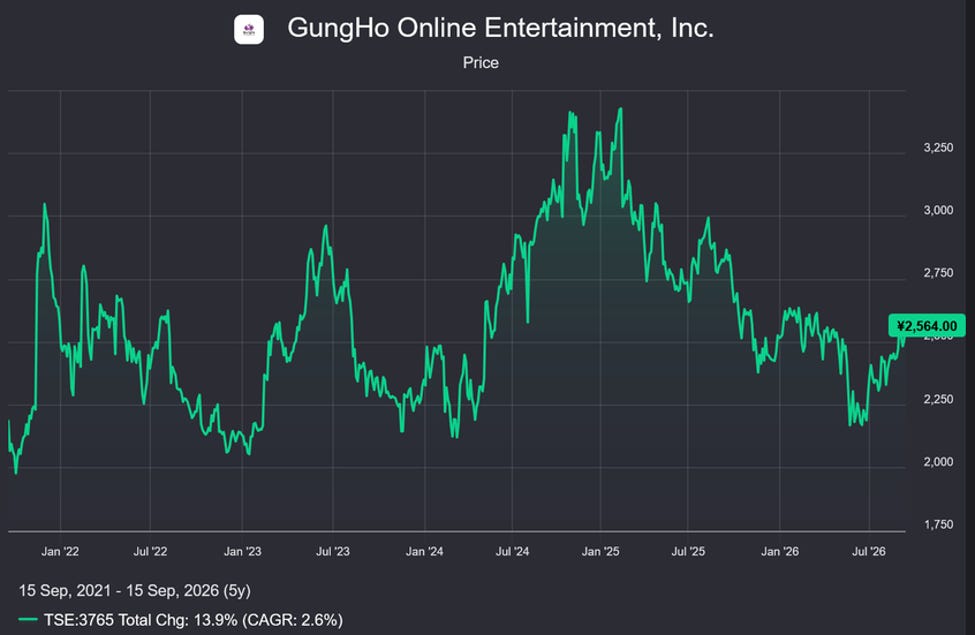
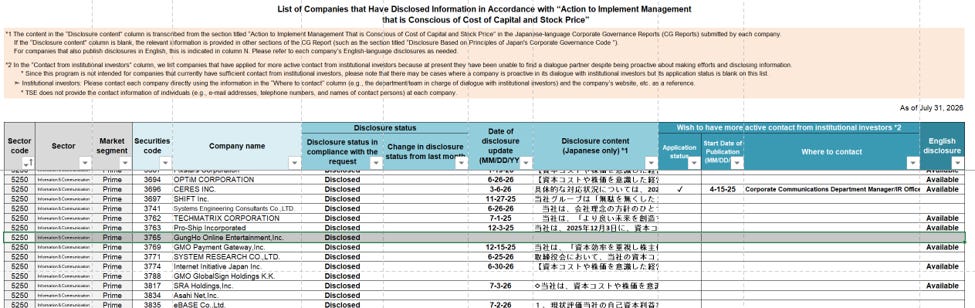
Change at Gravity is happening because of the changes at the parent level. In the background there has been significant pressure in Japan to improve capital allocation, including ‘on March 31, 2023, Tokyo Stock Exchange (TSE) requested that all listed companies on the Prime and Standard Markets take ‘action to implement management that is conscious of cost of capital and stock price.’” GungHo is on the list. https://www.jpx.co.jp/english/equities/follow-up/02.html
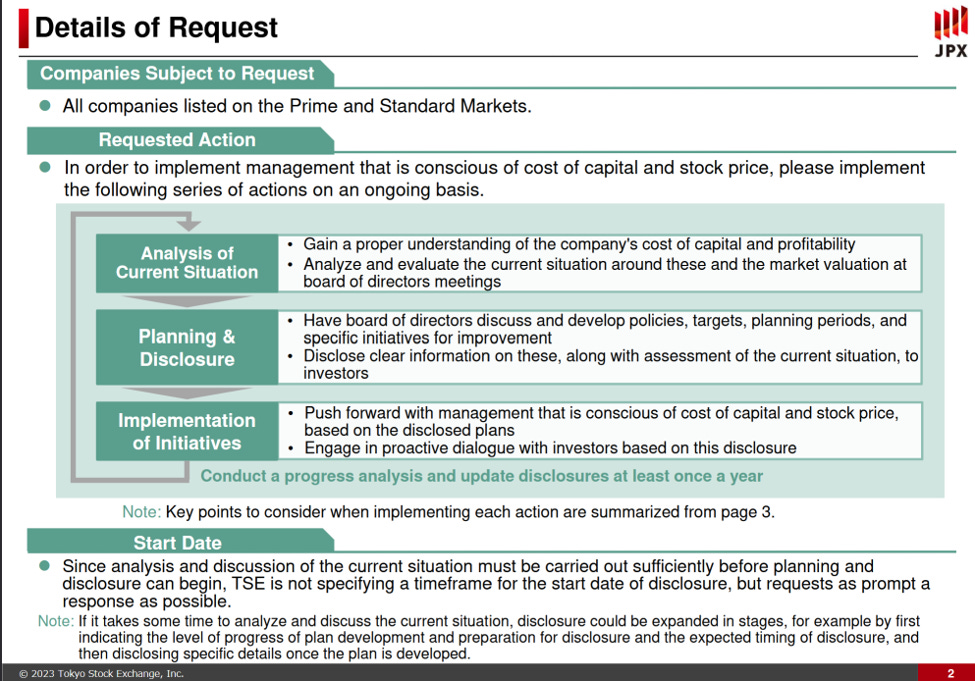
For GungHo (3765.JP), the trouble for the Board started with Strategic Capital’s campaign, which was facilitated by the company’s vulnerable ownership structure and poor track record of developing new IP (outside of Gravity/Ragnarok), spending over ¥100bn on roughly 20 titles since Puzzle & Dragons in 2012 without producing another hit. Unlike many closely-held Japanese firms, GungHo was “only” ~22% of voting rights controlled by Taizo Son (the younger brother of SoftBank’s Masayoshi Son) through Son Financial and related vehicles, leaving them open to minority shareholder pressure (GungHo held a massive treasury stock position of ~33% of outstanding shares prior to activist-driven cancellations.)
Strategic Capital disclosed an initial stake in GungHo on October 16, 2024 and was the start of their campaign against the company’s governance. As a side note, Strategic Capital has a lot of activism going on - https://stracap.jp/english/
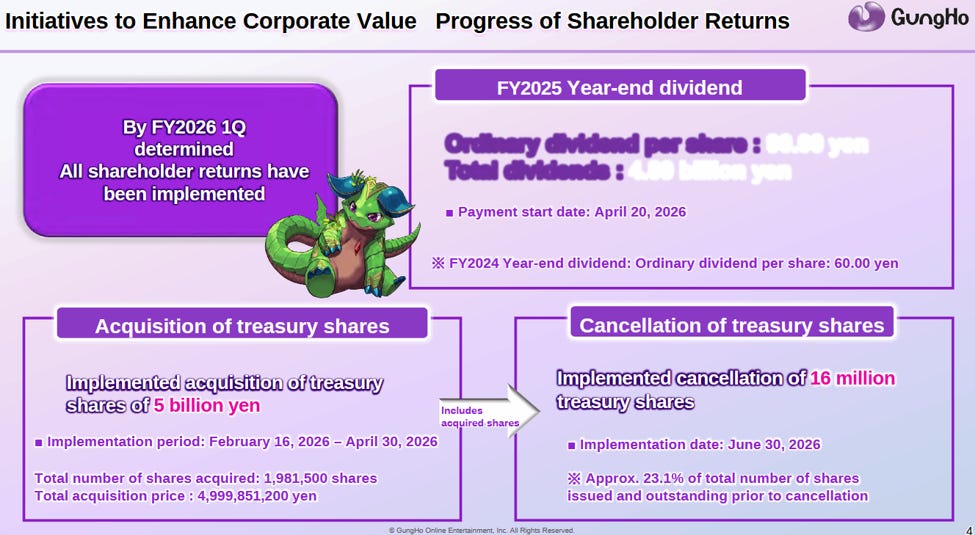
We find the whole situation quite funny. GungHo’s board officially rejected all of Strategic Capital’s shareholder proposals on February 13, 2025. And then Strategic Capital forced an EGM on September 24, 2025 with two proposals: relax the threshold for dismissing a director, and dismiss CEO Kazuki Morishita. The first passed (though the second failed), which was the tipping point. On February 13, 2026 the board unanimously opposed all ten shareholder proposals (which were all effectively from Strategic Capital and also LIM Japan Event Master Fund) ahead of the March AGM and all proposals were rejected at the AGM by Son and the majority of other shareholders. However, despite this, GungHo’s CEO stepped down, they introduced a 4% Dividend on Equity (DOE) target and raised its minimum consolidated payout ratio to 50% or higher. Strategic kept losing the actual votes but won in the end. And along the way Son was selling down shares.
Strategic kept losing most of the actual votes but won in the end, and now owns ~22% while Son was selling down shares along the way.
This all happens and then Sony announces a deal.
Sony Alliance
At the end of August, GungHo announced that its longtime key shareholder Son was being replaced by Sony and a new deal (closing December 2026).
At the Board of Directors meeting held today, GungHo Online Entertainment, Inc. (hereinafter the “Company”) resolved to conduct a secondary offering of its ordinary shares in connection with the transfer by SON Financial LLC, a major shareholder, the principal major shareholder and an other affiliated company of the Company, of all of its holdings of the Company’s ordinary shares to Sony Music Entertainment (Japan) Inc. (hereinafter “SME”) through an off-market bilateral transaction (hereinafter the “Share Transfer”), and, on the premise that SME will acquire the Company’s ordinary shares through the Share Transfer, to enter into a capital and business alliance agreement with SME (hereinafter the “Capital and Business Alliance Agreement”, and the capital and business alliance based on the Capital and Business Alliance Agreement is hereinafter referred to as the “Capital and Business Alliance”).
https://finance-frontend-pc-dist.west.edge.storage-yahoo.jp/disclosure/20260828/20260828527985.pdf
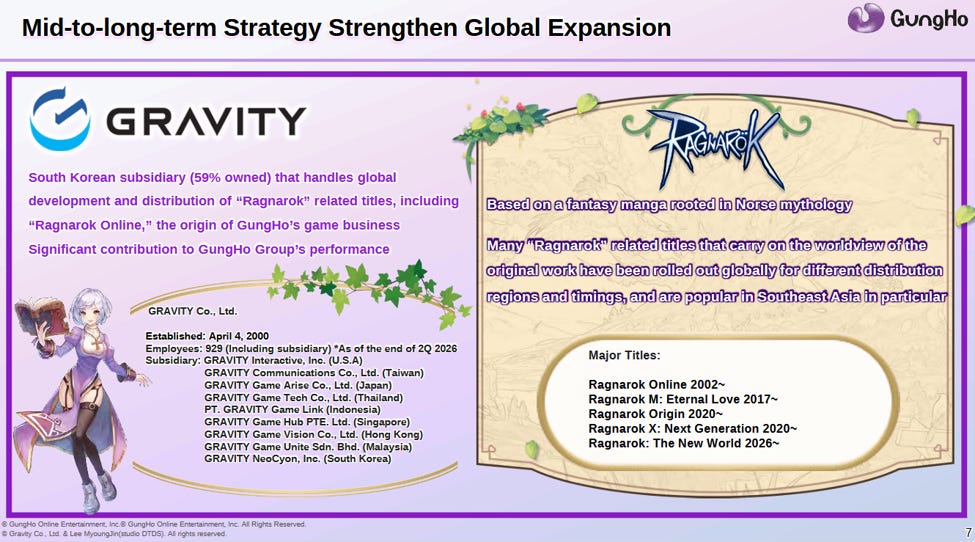
We view this as potentially good for Gravity over the long-term. Sony says it will be “exploring joint development and joint operation of smartphone games, console games, and PC games… promotion of collaboration initiatives for GungHo Games”. It specifically talks about smartphone, console and PC opportunities. That aligns well as Gravity is already trying to take Ragnarok away from being primarily a mobile-MMO franchise toward a broader IP ecosystem spanning PC/console titles, animation, music, concerts, merchandise and other entertainment formats.
